Demystifying Veri*Factu: What Spanish Small Businesses Need to Know
Veri*Factu sends billing records to the AEAT. We explain record integrity, how errors are corrected and what the QR code allows customers to check.
Royal Decree 1007/2023 regulates billing software systems (SIF) to prevent records being hidden or altered. VERI*FACTU is one compliance mode, which sends records to the AEAT; a non-VERI*FACTU mode also exists, with additional retention and control measures. It does not itself require a structured electronic invoice to be sent to the customer.
Scope and exclusions matter: the rules do not apply identically to every business. For example, taxpayers keeping VAT books through the Immediate Supply of Information (SII) are excluded from the regulation; the regional tax regimes must also be considered. Royal Decree-Law 15/2025 requires adaptation before 1 January 2027 for in-scope Corporate Income Tax taxpayers and before 1 July 2027 for the other taxpayers covered by Article 3.1, including many self-employed workers.
What immutability really means
Integrity requires that records cannot be altered or deleted without a trace. When an invoice is issued, the SIF generates a creation record; later corrections must preserve traceability. Software compliance is certified through its producer's responsible declaration for each version, not through prior AEAT approval.
Creation and cancellation records are chained chronologically to the system's previous record using a digital fingerprint. The technical specifications under Order HAC/1177/2024 and the AEAT define how that fingerprint is calculated. The aim is to detect changes to the history, not to prevent documented error correction.
What if you make a genuine mistake?
The law accounts for mistakes, but requires the history to be preserved. The solution depends on the error: cancelling a record and issuing a corrective invoice are not interchangeable. The AEAT explains the differences in its FAQs:
- Cancellation record: identifies a creation record generated in error without deleting it from the history.
- Corrective invoice (Factura Rectificativa): issued when an invoice must be corrected under the invoicing regulation; it generates its own creation record.
Both actions create their own chained records, so the full history is always documented.
Real-time transparency with the AEAT
In VERI*FACTU mode, the system sends billing records to the AEAT continuously, securely and automatically, immediately after generating them, under its transmission and response specifications. This reporting must not be confused with periodic tax returns or understood to replace them. An electronic signature on each record is not mandatory in this mode.
- 01
You create the invoice
Fill in the details and issue it from evoicy.
- 02
Recorded and linked
The record is linked to the previous one so alterations leave a trace.
- 03
Hacienda receives it live
It's sent securely to the Tax Agency the moment you issue it.
- 04
Verifiable record
The QR code checks the record's data with the AEAT; it does not certify the transaction's legality.
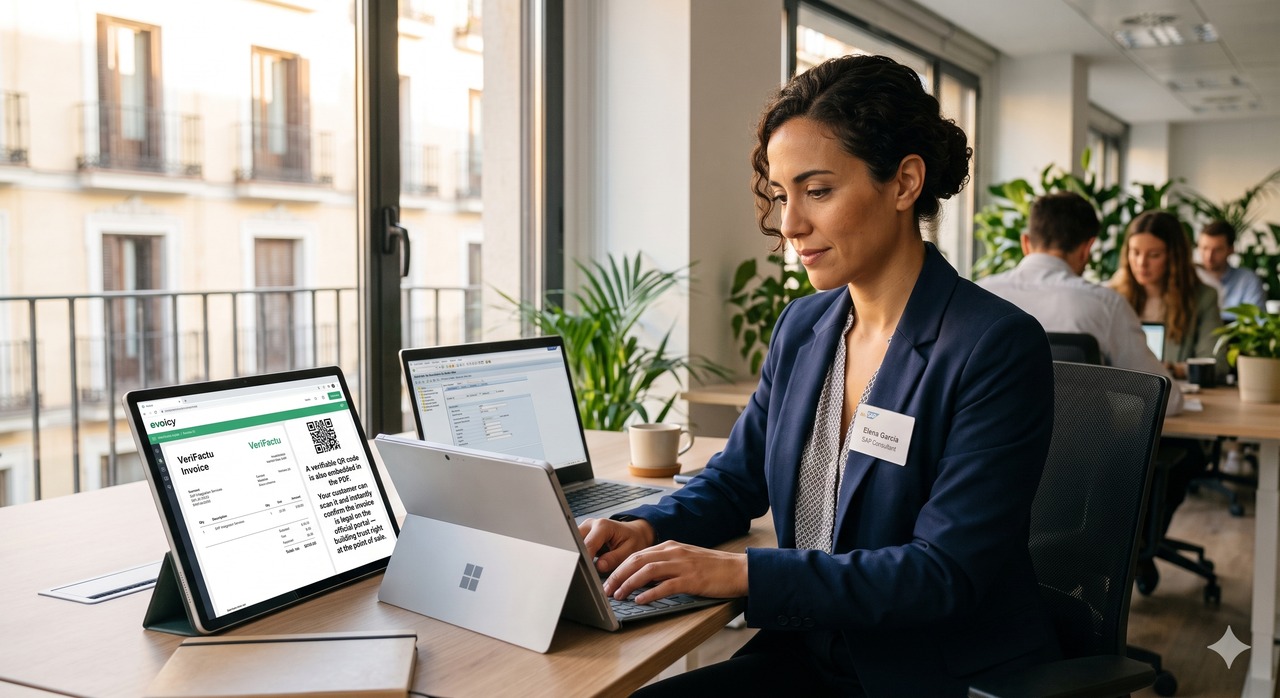
Invoices issued using an in-scope SIF include the required QR code or, for electronic invoices, the content it represents. In VERI*FACTU mode, customers can check that the record and its data appear on the AEAT portal. This does not certify the legality of the transaction or that all taxes are correct. In non-VERI*FACTU mode, the QR code lets customers submit information to the AEAT, but not check a previously submitted record.
Official sources and editorial review
Content checked against official sources on .
General information, not tax or legal advice. Scope, exceptions and timing depend on your circumstances. Check the current official texts and consult your adviser before making decisions.
- BOE — Royal Decree 1007/2023: billing software requirements
Scope and exclusions (Articles 3–4), record integrity (Articles 8–12), producer declaration (Article 13) and VERI*FACTU mode (Articles 15–16).
- BOE — Order HAC/1177/2024: billing software technical specifications
Chaining, creation and cancellation records, digital fingerprints, signatures and QR codes.
- AEAT — Official FAQs on VERI*FACTU systems (Spanish)
Immediate reporting, differences from non-VERI*FACTU mode, no mandatory record signature in VERI*FACTU, and QR record checking.
- AEAT — Billing records: cancellation (Spanish)
Preserving the original record and correcting according to the error; cancellation and a corrective invoice are not interchangeable.
- BOE — Royal Decree-Law 15/2025, Article 3: adaptation deadlines
Before 1 January 2027 for in-scope Corporate Income Tax taxpayers; before 1 July 2027 for the other taxpayers covered by Article 3.1.
- AEAT — Information note on extended billing software deadlines (Spanish)
Official confirmation of the 2027 deadlines and the preceding testing period.